
After a Georgia storm, a roof can look intact from the driveway while wind, hail, or falling debris has damaged shingles, flashing, vents, or the underlayment. Start with safety, document what you can see from the ground, and keep records of temporary protection before permanent work begins.
A storm-damage roof insurance claim in Georgia usually involves reviewing your policy, documenting the condition, notifying your insurer promptly, and arranging inspections. Your policy and insurer determine coverage, deadlines, deductibles, and payment. A roofing contractor can inspect the physical roof, document visible conditions, and prepare construction information, but cannot promise that a claim will be covered.
Need help documenting storm-related roof damage? Call (404) 445-8136 or request a roof evaluation through All In One Exteriors.
What Counts as Storm Damage to a Georgia Roof?
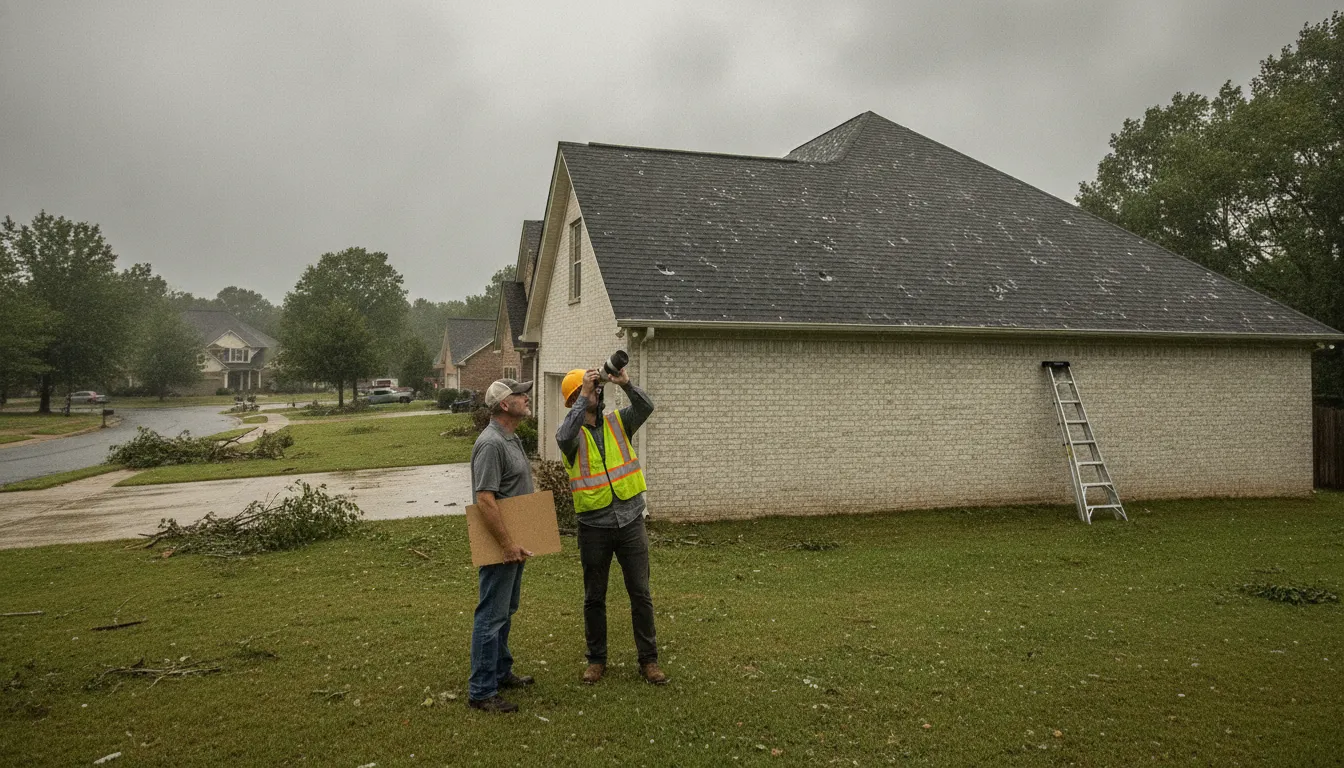
Storm damage is not always a missing section of roof that you can see from the driveway. Wind, hail, heavy rain, and falling branches can affect several roofing components at once. The visible problem may be a displaced shingle, while the more important concern is water entry beneath the roof covering.
Common visible signs after wind, hail, or falling branches
Strong wind can lift, crease, loosen, or remove shingles. Look from the ground for irregular rows, exposed underlayment, or shingle tabs that no longer lie flat. Hail may leave dents or impact marks on shingles, metal flashing, vents, gutters, and other exterior surfaces. A branch or tree can puncture the roof, crush a roof plane, damage the edge, or affect framing below it. Do not climb onto a wet or damaged roof to inspect it. Ground-level photographs can document what is visible while reducing the risk of a fall.
Water stains on ceilings, damp insulation, peeling paint, or a new leak may indicate that storm water entered through a damaged roof assembly. Georgia insurance guidance recommends photographing or recording damage before temporary repairs when possible and retaining receipts for protective work. Coverage and claim handling depend on the policy and insurer. Documentation is evidence, not a promise of reimbursement. Georgia’s insurance claim guidance also cautions that permanent repairs made before inspection may affect a claim.
Less obvious damage needs a professional assessment
Not every problem appears in a photograph. Wind can loosen flashing around valleys, chimneys, skylights, and wall intersections. Hail or debris can damage vents, pipe boots, ridge caps, and the roof surface without creating an immediate interior leak. Water may travel along decking or framing before it reaches a ceiling, allowing damage to develop after the storm has passed.
A contractor can inspect the roof system and document conditions from a safer position. The contractor cannot decide whether your insurer will cover a loss. Ask for observations and supporting photographs, not a diagnosis based only on a few exterior images. If water is entering the home or the roof has an exposed opening, take reasonable safety precautions and arrange temporary protection. All In One Exteriors documents storm-damage assessment, leak response, emergency repairs, and temporary measures such as tarping for Georgia property owners. Learn more about emergency roofing services if the damage needs prompt attention.
Before filing a storm damage roof insurance claim in Georgia, preserve photos, notes, receipts, and damaged materials when practical. Review your policy and contact your insurer for coverage-specific decisions. A professional inspection can help separate storm-related conditions from age, wear, or pre-existing damage, giving you clearer information for the next conversation.
What Should You Do First After a Georgia Storm?
- Make safety the first step. Stay away from downed power lines, unstable trees, sagging ceilings, broken glass, and water near electrical equipment. Do not climb onto a wet, steep, or damaged roof.
- Record what you can see safely. Photograph the roof from the ground, exterior walls, gutters, fallen branches, interior water stains, and affected belongings. Record the approximate storm date and when you discovered the damage.
- Limit additional damage when it is safe. Arrange professional temporary protection for an exposed opening or active leak when needed. Keep receipts and distinguish temporary protection from permanent repairs.
- Notify your insurer or agent promptly. Ask how your policy handles notice, temporary work, inspections, damaged materials, and claim documentation. Do not assume that every policy uses the same deadline.
- Keep a claim file. Save photos, videos, receipts, estimates, inspection reports, emails, letters, claim numbers, and notes showing the date, name, and role of each person you speak with.
- Arrange a professional roof inspection. A qualified roofer can document physical conditions and prepare repair information. The insurer and policy control coverage and payment decisions.
What Documents Should You Gather for a Roof Insurance Claim?
Gather the records that show what happened, what you observed, and what steps you took to protect the property. When practical, keep:
- Ground-level photos and video of the roof, siding, gutters, windows, trees, and interior water damage;
- The approximate date of the storm and the date you discovered each condition;
- Receipts and invoices for temporary protection, emergency service, and materials;
- Prior roof installation, repair, maintenance, warranty, and improvement records;
- Inspection reports, measurements, photographs, and written estimates;
- Your claim number and copies of emails, letters, forms, and conversation notes; and
- Damaged materials or property when the insurer asks you to preserve them for inspection and doing so is safe.
When Should You Report Storm Roof Damage?
Contact your agent or insurance company as soon as practical after discovering possible storm damage. Your policy may require notice within a particular period, and the applicable timing can depend on the policy and loss. Ask the insurer for the required notice process, claim documents, inspection instructions, and temporary-repair guidance. Georgia Office of the Commissioner of Insurance claim guidance also recommends complete information, organized records, and photos before temporary repairs when possible.
What Is a Proof of Loss?
A proof of loss is a written statement or form that some insurance policies require after a property loss. It may ask for information such as the date and cause of the loss, the property affected, the claimed amount, supporting records, and the policyholder’s statement about the damage. Not every claim uses the same form, and a roofing contractor cannot decide whether a proof of loss is required.
Read the policy and ask the insurer or agent for the exact instructions, form, supporting documents, and submission deadline that apply to your claim. Keep a complete copy of anything you submit and note when and how it was delivered. A contractor can provide measurements, photographs, and a repair estimate for the roof, but the policyholder remains responsible for following the insurer’s claim instructions.
How Do Supplements Work in a Roof Insurance Claim?
A supplement is additional construction information or scope submitted after an initial estimate when documented conditions, measurements, materials, code requirements, or concealed damage differ from the first scope. A contractor may provide photographs, measurements, material specifications, and an itemized estimate to explain the additional work. A supplement is not an automatic approval, and the insurer decides whether additional payment is owed under the policy.
Ask how the insurer wants supplemental information submitted, keep copies of every version, and avoid treating an estimate as a coverage decision. If additional damage is found after work begins, document it and ask the insurer how it wants the condition inspected before proceeding when circumstances allow.
How Should You Coordinate With Your Roofing Contractor and Insurer?
The property owner, insurer or adjuster, and roofing contractor have different roles. The owner provides accurate information and follows the policy. The insurer or adjuster evaluates the claim under the policy. The contractor inspects roofing conditions, documents construction needs, and performs authorized work.
Share the claim number, inspection dates, photographs, estimates, and written scopes with the appropriate parties. Compare the adjuster’s scope with the contractor’s scope line by line, ask about differences in materials or quantities, and request written explanations for disputed items. Confirm who is responsible for temporary protection, the deductible, uncovered work, and any required approvals before permanent repairs begin.
Want a roof condition documented after a Georgia storm? Call (404) 445-8136 or request a roof evaluation from All In One Exteriors.
How Does a Storm Damage Roof Insurance Claim Work in Georgia?
A storm damage roof insurance claim in Georgia usually moves through several stages. From reviewing your policy to documenting damage, notifying the insurer, completing inspections, and deciding how repairs should proceed. The exact sequence, deadlines, deductible, exclusions, and payment terms depend on your policy and insurer. A roofing contractor can help assess visible damage, document conditions, and prepare repair information, but the insurer controls coverage and the claim decision.
1. Review your policy and protect the property
Start by reviewing the sections that address wind, hail, fallen trees, water intrusion, deductibles, exclusions, actual cash value, and replacement cost. Georgia’s Office of the Commissioner of Insurance advises homeowners to know what their policy covers, excludes, and requires before filing a claim. Read the official Georgia insurance claim tips for guidance from the state insurance office.
If the roof is leaking or exposed, take reasonable temporary steps to limit additional damage when it is safe to do so. A tarp or other temporary protection may be appropriate, depending on the circumstances and your policy. Keep receipts for emergency work and materials. Do not climb onto a damaged roof or attempt repairs that create a safety risk.
2. Document the damage and notify your insurer
Before temporary work begins, photograph or record the roof and related damage from safe locations. Capture displaced or missing shingles, damaged flashing, fallen limbs, interior water stains, damaged ceilings, and affected personal property. Keep damaged materials when practical until the insurer or adjuster has had an opportunity to inspect them. Record the storm date, when you discovered the damage, and any steps taken to protect the home.
Notify your agent or insurance company as soon as possible. Policies may impose a notice deadline, so do not assume there is one universal Georgia filing period. Provide complete and accurate information, including photographs, receipts, contractor reports, and prior repair records when requested. Keep copies of emails, letters, estimates, and claim forms. Also record the names, titles, dates, and key points from phone or in-person conversations.
3. Arrange inspections and compare the scope of work
Your insurer may send an adjuster to inspect the property. You may also arrange a professional roof inspection so a qualified contractor can identify storm-related conditions, explain emergency needs, and prepare an estimate. The contractor’s findings can support your records, but they do not replace the insurer’s coverage review.
During the adjuster’s visit, provide access to the roof and interior areas affected by the storm. Share your documentation and describe what you observed without guessing or exaggerating. Ask how the insurer will handle temporary repairs, depreciation, the deductible, and any additional damage discovered later. Before permanent repairs begin, confirm whether the insurer requires an inspection or other approval. Georgia insurance guidance warns that permanent repairs made before inspection may affect a claim.
4. Review the coverage decision before repairs
After reviewing the policy, inspection findings, and estimates, the insurer may issue a scope of work, settlement offer, partial decision, or denial. Ask for an itemized explanation of any settlement and compare it with the documented damage and contractor estimate. Do not assume an estimate or initial payment represents the final repair plan, and do not rush into accepting a settlement.
If you disagree with the decision, ask the insurer to identify the specific policy language involved. If the claim is denied, request a written explanation stating the reason and relevant policy language. Once the scope and payment process are clear, coordinate necessary repairs with a qualified contractor. All In One Exteriors can help Georgia homeowners evaluate storm damage, document conditions, and understand repair or replacement options, while coverage decisions remain with the insurer.
Will Homeowners Insurance Cover Storm Roof Damage?
Coverage depends on the cause of the damage, the policy language, the roof’s condition, and the facts documented during the claim. A storm damage roof insurance claim in Georgia should not be treated as automatically approved or denied based only on what is visible from the ground. Review your policy, including exclusions and deductibles. Ask the insurer how the applicable provisions may affect your situation.
| Storm cause or situation | What may apply | Question to ask the insurer |
|---|---|---|
| High winds or a tornado | Georgia insurance officials state that standard homeowners policies generally cover high-wind and tornado damage. Policy terms, limits, exclusions, and deductibles still apply. | What wind-related damage is covered under my policy, and what deductible or exclusions apply? |
| Flooding or rising water | Flood damage is generally not covered by a standard homeowners policy. Separate flood insurance may be available through the National Flood Insurance Program when the community participates. | Is this damage being classified as flood damage, wind-driven rain, or another cause, and which policy would apply? |
| Rain entering through a storm-damaged roof | Rain-related interior damage may be considered differently when the roof was damaged during the storm. The insurer must evaluate the cause and policy language. | What evidence do you need to connect the interior water damage to the storm-damaged roof? |
| Older, worn, or poorly maintained roofing | Pre-existing wear, maintenance issues, exclusions, or policy conditions may limit or affect coverage. Do not assume a storm caused every roof defect. | Which portion is attributed to the storm, and which specific policy language supports that determination? |
| Actual cash value versus replacement cost | Actual cash value accounts for depreciation. Replacement cost coverage may use current prices for covered contents, but roof settlement terms and conditions should be confirmed directly with the insurer. | Is my roof evaluated on an actual cash value or replacement cost basis, and what conditions must be met? |
Before making permanent repairs, ask whether an inspection is required and keep photos, videos, estimates, and receipts. Georgia’s Office of the Insurance Commissioner advises homeowners to contact their agent or insurer promptly after a disaster. Protect the property from further damage when possible, and retain documentation. Its severe-weather safety guidance also explains the distinction between standard homeowners coverage and separate flood insurance.
A roofing contractor can document observable conditions, identify areas that need temporary protection, and prepare repair information. The insurer, however, decides how the policy applies. If the claim decision is unclear, request the relevant policy language and a written explanation rather than relying on assumptions.
What Should You Tell an Insurance Adjuster?
When you speak with an insurance adjuster, focus on what you observed and what you can document. Explain when you noticed the damage, what the storm conditions were like, and which areas of the property appear affected. Describe visible facts such as missing shingles, exposed materials, water stains, or a leak. If you are unsure when damage occurred or what caused a particular condition, say so. Do not guess, exaggerate, or describe damage you cannot verify.
Share complete information and preserve your records
Have your policy information, photos, videos, repair receipts, inspection findings, and contractor estimates organized before the conversation. Tell the insurer about all known damage, including interior effects and temporary measures taken to protect the home. Georgia insurance officials advise claimants to provide complete, correct information because incomplete or incorrect details can delay claim processing. Their insurance claim guidance for Georgia homeowners also recommends keeping copies of correspondence and recording the date, name, title, and substance of each phone or in-person contact.
Keep a simple claim log. Note when you reported the loss, who inspected the property, what documents you sent, and what the adjuster said would happen next. Save emails, letters, text messages, estimates, receipts, and photographs in one location. Do not discard damaged materials or personal property unless the insurer has reviewed them or has given you instructions. If emergency work is necessary, document the condition first when it is safe and keep every related receipt.
Ask for an itemized explanation
You can ask the adjuster to explain how the settlement or estimate was calculated. Georgia guidance recommends requesting an itemized explanation of the claim settlement offer. Ask which covered damage is included, which items were omitted, and whether the estimate reflects temporary work, permanent repairs, or both. If you disagree with the decision, ask the insurer to identify the specific policy language supporting its position. For a denial, request a written explanation stating the reason and the relevant policy language.
This is general information, not legal or insurance advice. Your policy, insurer, and the facts of the loss control the claim decision. Avoid signing a settlement or authorization you do not understand, and consider qualified legal or insurance guidance if a significant dispute remains.
When Should You Repair or Replace a Storm-Damaged Roof?
The choice between a repair and a full replacement depends on more than one missing shingle. A qualified inspection should consider how much of the roof was affected, where the damage occurred. The roof’s age and prior condition, and whether the existing materials can be matched. The right scope should reflect the documented loss, not a one-size-fits-all recommendation.
When a repair may be appropriate
Repair may make sense when storm damage is limited to a defined area and the underlying roof system remains sound. Examples can include a small number of displaced or damaged shingles, isolated flashing damage, or a localized leak caused by a storm event. The inspection should look beyond the most visible defect. Wind or hail can affect vents, pipe boots, ridge caps, underlayment, and areas around roof penetrations.
Temporary mitigation may be necessary before permanent work begins. If the roof is open or water is entering the home, a contractor may recommend a tarp or another temporary protective measure to limit additional damage. Georgia insurance officials recommend photographing or recording damage before temporary repairs when possible, keeping receipts, and checking with the insurer about required steps. Permanent repairs made before an inspection could affect how a claim is evaluated. Review the guidance from the Georgia Office of Commissioner of Insurance and follow your policy’s instructions.
When replacement deserves consideration
Replacement may be more appropriate when damage is widespread, affects multiple roof planes, or compromises the roof’s ability to protect the structure. Age and pre-storm condition also matter. A roof that was already near the end of its service life, had recurring leaks, or showed extensive wear may not be a good candidate for isolated repairs. The inspection should distinguish storm-related damage from deterioration that existed before the event.
Matching is another practical issue. Older shingles, discontinued profiles, faded colors, or unusual materials may be difficult to match without creating an obvious patchwork appearance. If a repair cannot restore the roof’s weatherproofing or appearance reliably, discuss roof replacement options with the contractor. For planning context, factors that influence roof replacement costs in Georgia include materials, labor, permits, and project scope. Avoid treating an online estimate as a claim determination or guaranteed price.
Let the inspection define the scope
A thorough inspection documents the location and extent of damage, the condition of the roof system, interior water intrusion, and any temporary work already completed. Ask for a clear explanation of what can be repaired, what may require replacement, and which observations relate to the storm versus prior wear. The insurer decides coverage under the policy, while the contractor can provide an independent assessment and a repair or replacement scope.
All In One Exteriors serves Alpharetta, Marietta, Johns Creek, Atlanta, and nearby North Georgia communities. Its documented storm-damage services include assessment, documentation, leak response, emergency repairs, and temporary protective measures. A free inspection can help establish the next practical step, whether that is storm damage repair, roof repairs after storm damage, or a larger project.
Frequently Asked Questions
How long do you have to claim roof damage from a storm?
There is no single deadline for every Georgia homeowner. Your policy may set a notice or filing timeframe, and the requirement can depend on the type of damage and the insurer. Review your policy and contact your insurer promptly after making the property safe. Keep records of the storm date, damage, temporary repairs, photos, and every conversation.
Does homeowners insurance cover roof damage caused by storms?
Coverage depends on your policy, the cause of the damage, exclusions, deductibles, and the roof’s condition. Wind or hail damage may be treated differently from wear, poor maintenance, or excluded causes. Your insurer decides coverage under the policy, so request a written explanation and ask what documentation is needed before assuming a repair or replacement will be covered.
What is considered storm damage to a roof?
Storm damage can include missing or displaced shingles, hail impacts, damaged flashing or vents, fallen branches, and water intrusion caused by a storm-related opening. Some problems are not visible from the ground. Stay off the roof when conditions are unsafe and arrange a qualified inspection rather than relying only on photographs or a ground-level view.
What should you not say to a roof insurance adjuster?
Do not guess about the roof’s age, cause of damage, repair history, or the extent of loss. Do not exaggerate, speculate, or describe damage you did not observe. Give a factual account, share your photos and records, and correct errors promptly. You can ask questions and take time to review the estimate before discussing repair or replacement decisions.
Schedule a Storm-Damage Evaluation
If your Georgia roof may have storm damage, All In One Exteriors can help document visible conditions and explain practical repair or temporary-protection next steps. Coverage, deadlines, deductibles, and payment remain subject to your policy and insurer.